The EU is building further alliances.
In Manila, on Tuesday, September 22, the European Union and the Philippines agreed on the substance of a free trade agreement, one that revealed the shape of Europe’s strategy in Southeast Asia. The deal, giving Philippine exporters permanent preferential access to the EU market of roughly 450 million consumers, follows agreements already in force with Singapore and Vietnam, an Indonesian pact awaiting approval, and Thai talks entering what Bangkok hopes to be their final round.
Together, these agreements tie the EU, already the third-largest trading partner for the ASEAN bloc, and its largest source of foreign direct investment (FDI), into several of the largest economies in the region—but not the bloc as a whole. The EU is building its Southeast Asian relationship nation by nation, undermining the prospects of a bloc-to-bloc agreement that both sides still profess to want.
The joint statement that emerged from Manila is conscientious in the way such documents are; it records that two-way goods trade reached $318.8 billion in 2025, whilst warning against unilateral trade measures, and calls a closer partnership “not only essential but also imperative.” The most concrete deliverable that emerged is a set of digital trade principles that the statement itself describes as non-binding; nowhere in its nine paragraphs does it mention a region-to-region free trade agreement.
There is a great deal of history here that the silence betrays. Bloc-to-bloc negotiations opened in 2007, and were shelved within two years. A later review found that the two sides’ positions remained too far apart, and in 2022, the working group meant to sketch a future framework was redirected toward sectoral cooperation on digital, environmental, and supply-chain questions. In January 2026, the EU’s ASEAN ambassador called a regional deal a long-term objective, signaling that talks were unlikely before 2027. ASEAN governments still speak of an ambitious region-wide agreement—while Brussels keeps negotiating by nation.
The language that Brussels uses is indicative of reaching the “long-term objective” by other means, however, referring to each national agreement as “building blocks.” Repeated in Manila, this framing is that each bilateral trade deal is a step toward stronger region-to-region ties, and the EU–ASEAN Business Council has urged Thailand and Malaysia to adopt the same relationship.
But the ties that bind are loose here. Each is a separately negotiated settlement—its own tariff schedules, its own rules of origin, its own sustainability chapter calibrated to what a single government would concede. A concession to Manila does not travel to Bangkok. As a result, the trade architecture is less a foundation than a set of parallel corridors, each opening onto and leading into Brussels, but not into one another. If a region-to-region agreement between ASEAN and the EU is ever negotiated, the first task would be the reconciliation and rationalization of half a dozen texts that were radically different—by design.
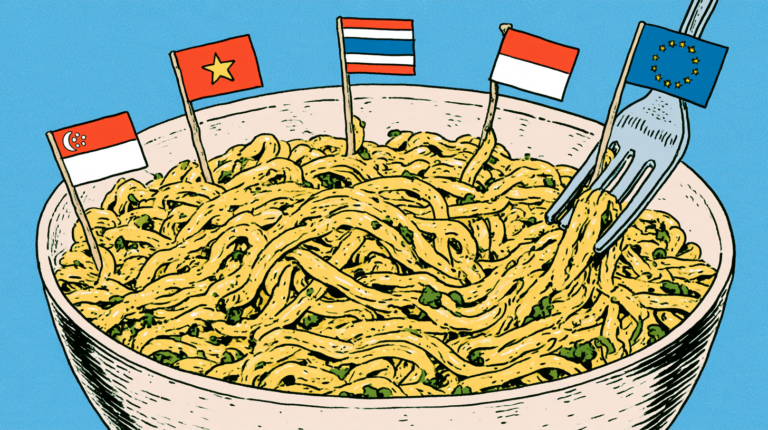
This has very real ramifications for firms looking to operate in Southeast Asia; a European manufacturer supplying Philippine factories with Thai or Vietnamese components will find that wherever those parts count as originating from will depend on which agreement is invoked and what cumulation each one permits. Economists call the result a noodle bowl, but for exporters it will create yet further regulative burdens. The statement does not shy away from this, worrying about the costs of an unpredictable environment and the impacts it will have on micro, small, and medium-sized enterprises—but it does fail to mention that the architecture being constructed by this overlapping network of deals will compound those costs, falling lightest on firms large enough to afford the legal experts capable of navigating them.
This arrangement suits Brussels: negotiating one government at a time allows the Commission to calibrate its demands to each partner’s appetite, and it sidesteps the consensus rule of an 11-member bloc that includes Myanmar, where even investment talks have been on hold for years. Plainly, however, it suits ASEAN’s more ambitious nations too, outpacing the slowest members and seizing the advantages where they present themselves.
The Philippines, hit by US tariffs and by the price shock of the increased energy costs around the world, had its own reasons for haste—the deal announced in September will also replace the preferences it currently enjoys in the EU’s General Scheme of Preferences Plus (GSP+ scheme) with permanent access. Yet Europe is not the only one looking to increase access to the region—two days before meeting with the EU’s representatives, the same Philippine ministers met with Washington, whose $550 billion of goods trade with ASEAN dwarfs Europe’s.
The trade-off to bilateralism, inevitably, is the cost to ASEAN’s weight as a bloc, with external market access being disbursed one member at a time, on terms drafted in (and, almost certainly, designed to favor) Brussels. European business is not waiting for the Southeast Asian region to catch up: 78% of respondents to the EU–ASEAN Business Council’s survey expect trade and investment in ASEAN to rise, meaning that capital is encouraged by the current setup, and sees no reason for it to change.
The 50th anniversary of ASEAN–EU dialogue falls in 2027, and ASEAN members want to mark it by elevating ties to a comprehensive strategic partnership. But if, by then, ASEAN has allowed its member nations to settle their terms one by one, will the bloc have anything more to add?